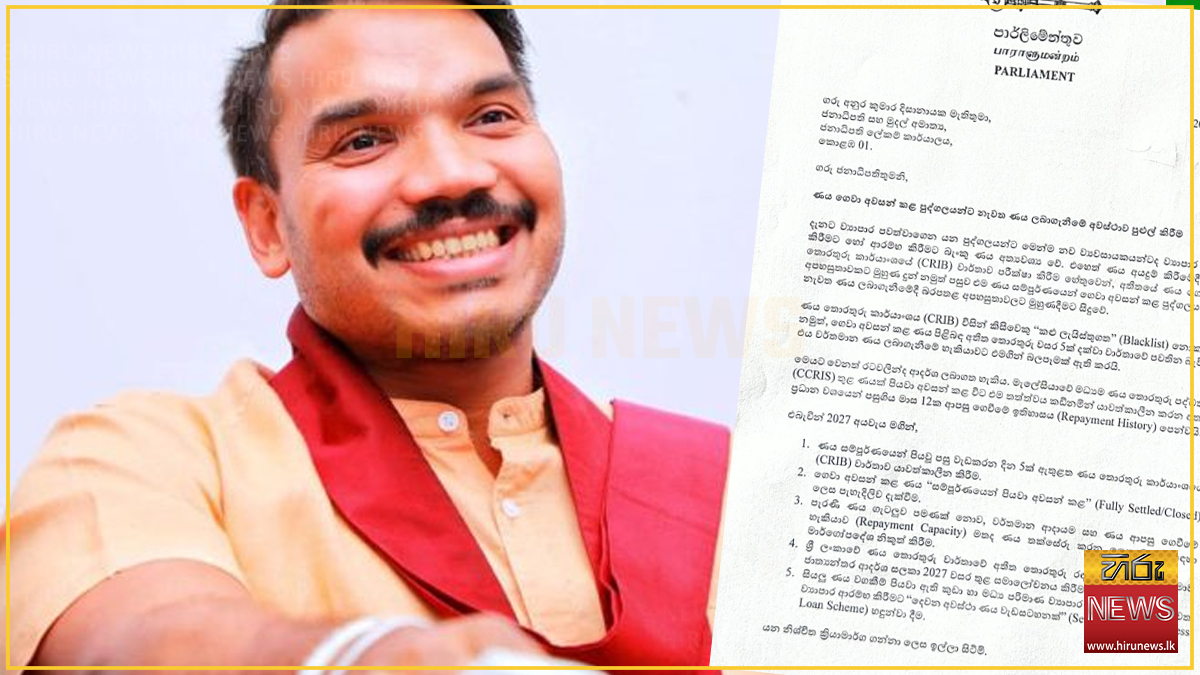
SLPP National Organizer and MP Namal Rajapaksa has written to President Anura Kumara Dissanayake asking that the 2027 Budget change how long settled loans remain visible in Credit Information Bureau records, arguing that borrowers who have paid their debts in full are still being refused new credit because of them.
Past loan information stays on a CRIB file for up to five years after the debt is cleared, Hiru News reported, which the letter says creates serious difficulties for individuals and entrepreneurs seeking fresh borrowing.
The letter is addressed to Dissanayake in both his capacities — President and Minister of Finance — according to the Daily Mirror, which filed at 3.14 p.m. on Wednesday.
The five proposals
- Update CRIB reports within five working days of a loan being settled in full.
- Mark settled loans clearly as “Fully Settled/Closed”.
- Issue guidelines directing banks to assess applications on the borrower’s current income and repayment capacity, not past records alone.
- Review the retention period for historical credit information during 2027, against international practice.
- Introduce a “Second-Chance Business Loan Scheme” for micro, small and medium enterprises that have cleared all prior obligations.
The qualifier Hiru leaves out
The Daily Mirror’s account carries a distinction the Hiru filing does not: the five-year retention is not a blacklist. CRIB does not blacklist individuals; it reports history, and lenders draw their own conclusions. That matters, because the widespread belief that CRIB maintains a blacklist is itself part of what the letter is responding to — and it changes the target of the request from an institution refusing borrowers to the lending practices built on top of its data.
Malaysia’s window is twelve months, not five years
Only the Daily Mirror names the comparator. Rajapaksa cites Malaysia’s Central Credit Reference Information System (CCRIS), which updates a loan’s status once it is repaid and primarily reflects repayment history over the preceding 12 months.
Set against Sri Lanka’s five years, that is the quantified core of the request: a retention window roughly five times longer than the model being held up.
Hiru renders this only as “models from countries like Malaysia” and gives no figure. The letter photographed by Hiru resolves it — the document itself carries “CCRIS”, a reference to a 12-month repayment history, and the English phrase “Fully Settled/Close” among its five numbered points, confirming the Daily Mirror’s fuller reading.
The Bureau has already done a version of this
What the letter asks for is not without precedent. In April, CRIB opened a six-month credit relief window for borrowers hit by Cyclone Ditwah: payments delayed by the disaster were not reported as overdue, records were updated to reflect the support given, and new recovery lending was tagged separately. Reporting of eligible borrowers began on 1 March 2026.
That scheme did three of the things now being requested — suppressing an adverse marker, updating records to reflect a changed status, and flagging a distinct category of loan. It was introduced under guidance from the Central Bank, not through a Budget.
CRIB is a creature of the Credit Information Bureau of Sri Lanka Act No. 18 of 1990. Whether a Budget is the instrument that can alter a retention period set under that Act and administered on Central Bank guidance is not addressed in either filing.
Who actually reads these files
The Bureau’s own numbers suggest borrowers rarely see the records being described. CRIB issued 13.46 million credit and analytical reports in 2025, up 41% on the year. Citizen self-inquiries through its MyReport service came to about 77,000 — roughly 0.6% of the total. Usage remains overwhelmingly by lenders querying applicants.
There is also a point of agreement the letter does not claim. CRIB chairman K.G.P. Sirikumara told the Bureau’s 36th AGM in September that credit intelligence should let lenders move toward “data-driven, risk-calibrated credit underwriting frameworks that empower MSMEs” — close to the third and fifth proposals in substance, from the institution whose rules are at issue.
Not reported: neither filing says how many borrowers are affected, whether the Finance Ministry, the Central Bank or CRIB has responded, whether the retention period can be changed without amending the 1990 Act, what a second-chance scheme would cost or who would carry the credit risk, or whether any lender has been asked about the proposals. Neither gives the date of the letter.